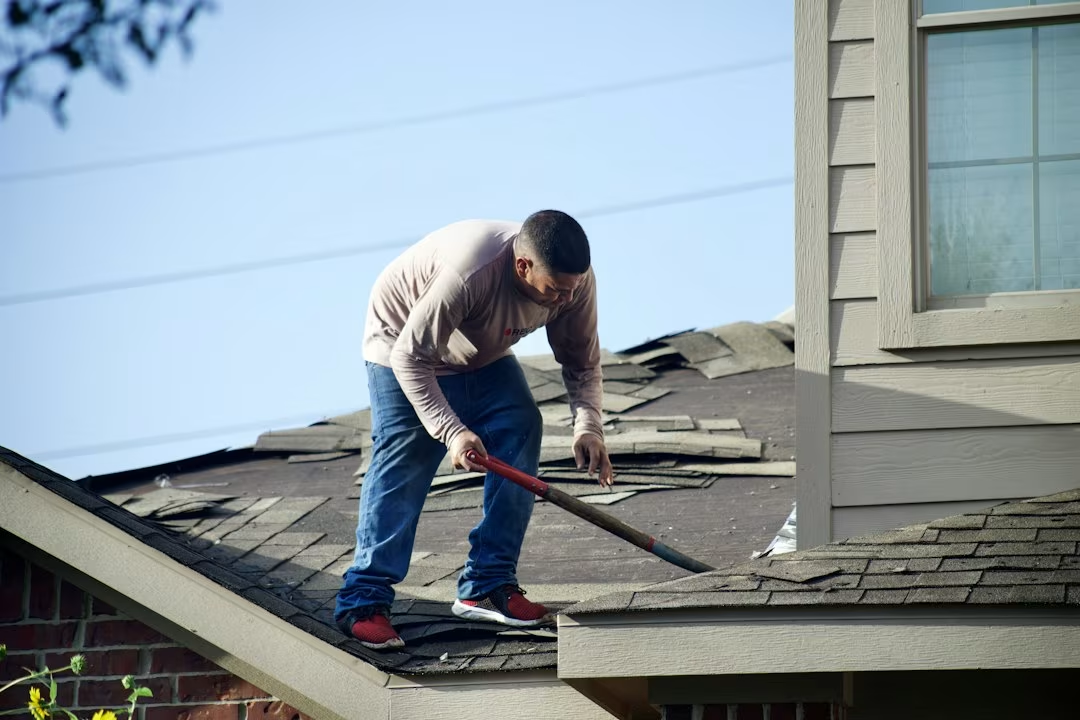
Colorado's Front Range sees some of the most damaging hail in the country, and the spring and summer storm seasons produce a predictable wave of roof, siding, window, and gutter claims. Insurers process those claims in bulk — and when adjusters are moving fast, homeowners routinely receive scopes that miss damage, depreciation holdbacks they don't understand, or flat denials blaming "wear and tear." This guide covers how hail and wind claims go wrong in Colorado and the legal rights that protect you.
How Hail and Wind Claims Get Underpaid
Partial scopes — the estimate covers the slope facing the storm but ignores collateral damage to siding, soft metals, window wraps, and fencing.
Repair-versus-replace disputes — the insurer prices spot repairs for a roof that no contractor will warranty without full replacement, or ignores matching problems when discontinued shingles can't be patched invisibly.
"Wear and tear" or "pre-existing damage" denials — age-related exclusions get stretched to cover fresh storm damage, especially on older roofs.
Depreciation confusion — homeowners accept the actual-cash-value check and never collect the recoverable depreciation they're owed after repairs are completed.
Slow-walking — inspections, re-inspections, and engineer reports that stretch a straightforward roof claim across seasons while tarps fail and interior damage spreads.
Your Rights When the Insurer Acts Unreasonably
Colorado law gives homeowners real leverage. Under C.R.S. § 10-3-1115, an insurer may not unreasonably delay or deny payment of a claim for benefits owed to a first-party claimant — and a delay or denial is unreasonable when the insurer acts without a reasonable basis. If that happens, C.R.S. § 10-3-1116 lets you sue to recover two times the covered benefit, plus reasonable attorney fees and court costs. That fee-shifting is what makes it economical to fight even a mid-sized hail or wind underpayment — the insurer, not you, bears the cost of being wrong.
Colorado also defines unfair claim settlement practices in C.R.S. § 10-3-1104, which include failing to conduct a reasonable investigation and failing to attempt a prompt, fair settlement once liability is reasonably clear. A pattern of lowballing, re-inspections that go nowhere, or unexplained silence maps onto that list more often than homeowners expect. Common-law bad faith claims can apply alongside the statute as well.
ACV, Replacement Cost, and Recoverable Depreciation
Most Colorado homeowner policies pay storm claims in two stages. The first check is actual cash value (ACV) — the replacement cost minus depreciation for the roof's age and condition. The remaining recoverable depreciation is paid after you complete repairs and submit the invoices, subject to the deadlines in your policy. Two things go wrong here constantly: homeowners treat the ACV check as the full settlement and never claim the depreciation they're owed, or the depreciation applied is so aggressive that the ACV payment won't fund a deposit with any legitimate roofer. Both are worth challenging — depreciation is an estimate, not a fact, and the insurer must be able to justify it.
The Matching Problem
Hail rarely damages every slope and every elevation equally, and insurers like to pay for the damaged portions only. But when your shingle or siding product is discontinued, a partial repair leaves a visibly mismatched home — and a diminished one. Whether and how far the insurer must pay to achieve a reasonably uniform appearance depends on your policy language and the facts, and it is one of the most commonly surrendered issues in Colorado storm claims. If the adjuster's scope patches discontinued materials, get the repair-versus-replace question reviewed before you accept it.
Practical Steps Before You Accept the Insurer's Number
Document immediately — date-stamped photos of the roof, elevations, soft metals, and any interior leaks before temporary repairs.
Get an independent scope — a reputable local roofer or public adjuster's estimate tells you whether the insurer's scope is honest before you cash anything.
Put disagreements in writing — ask the adjuster to identify, in writing, the policy basis for every line they cut.
Report on time, but don't panic about timing fights — insurers sometimes argue late notice; Colorado law treats that defense more narrowly than adjusters suggest. See our guide on late notice and Colorado claims.
When to Involve a Lawyer
If the gap between your contractor's scope and the insurer's scope is five figures, if a denial rests on a stretched exclusion, or if the file has gone quiet for months, it's time for a legal review. Our Colorado insurance claim practice page explains how we approach delay and denial cases, and our deeper guide to Colorado insurance bad faith law covers the statutory remedies in detail. For other loss types, see property damage insurance claims. Hollington Law Firm represents Colorado homeowners against insurers statewide — consultations are free.
Have Questions About Insurance Disputes?
Our experienced construction defect attorneys are here to help. Schedule a free 15-minute screening call to discuss your situation.